

Earlier this week, ARPN’s Daniel McGroarty shared his views on the coming tech metal age and its policy implications at In the Zone 2019 – Critical Materials: Securing Indo-Pacific Technology Futures – a conference hosted in cooperation with the University of Western Australia to look at critical mineral resource issues through the prism of the Indo-Pacific region.
The following is a transcript of his speech, as delivered.
Are we Ready for the Tech Metals Age? Thoughts on Critical Minerals, Public Policy and the Private Sector
By Daniel McGroarty
Thank you, Gordon [Flake, Chief Executive Officer, Perth USAsia Centre, University of Western Australia], for this opportunity to be In the Zone with so many of the key thought-leaders and decision-makers in the critical materials space.
As I start, a quick comment on where I’m coming from: I’ve served in the U.S. Government, at the White House and the Pentagon, and I now serve on the advisory boards of companies developing U.S. sources of a dozen of the metals and minerals on the US Critical List – one of those being Rio Tinto/U.S.
…so the points I want to share today come from my efforts to bring a public policy perspective / to private sector projects.
Think of it this way: Is there a way to align a private project to key public policy goals – in a way that advanced the interests of both?
If it sounds simple, as many of you know — it’s anything but.
Try as it might, the private sector has a very hard time meshing to the pace of government policymaking – I’m being diplomatic here — and policymakers have nothing in their mandate that requires them to appreciate — to really feel — the pressures of private sector competition.
Same planet, different worlds.
But as we’re seeing here today, the Critical Minerals Challenge is a huge challenge – and if we are collectively going to meet it, private sector leaders and public policy makers are going to have to perform a thought-experiment – a shift in mindset — to see the challenge from both sides, to find the common ground to move us forward.
Critical Minerals is a huge challenge. It’s so often said – we don’t step back to see the context.
Much of human progress was built with – literally – a handful of metals and minerals. It goes back to the early markers of human progress:
We had the Bronze Age – copper and tin – and the Iron Age to follow.
Geologically, the rest of the Periodic Table was ready and waiting, but we – as human-makers – we had no use for it.
It’s different now.
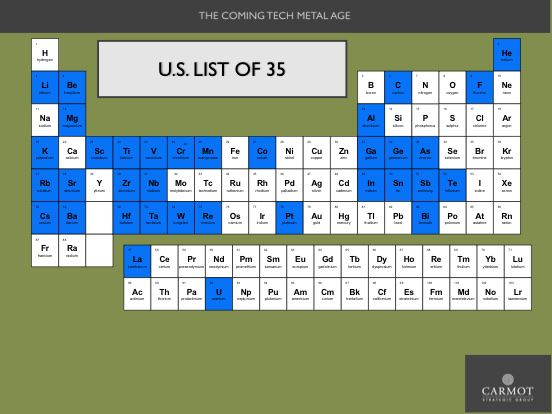
Take the U.S. Critical Minerals List: 35 minerals and metals – but really, as elements, it’s more than that. The rare earths count as 2 – Scandium gets its own mention – not 17, and the PGMs count as one, not 6.
Add them all in — and the U.S. List grows to 55.
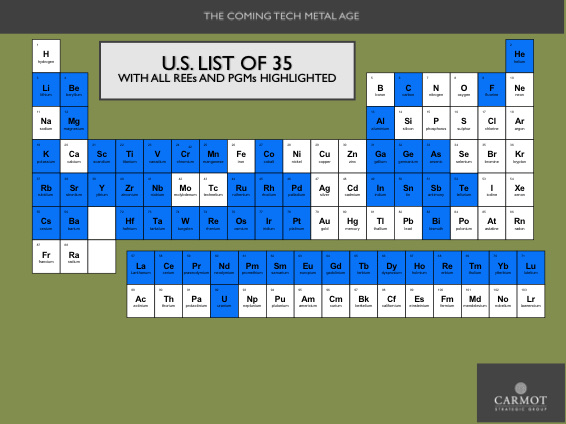
But wait: there’s more.
If we overlay on top the U.S. List the Australian and Japanese and EU critical lists, and add the unique elements, we get 10 more:
 A total of 65 in all.
We’re sneaking up on two-thirds of the naturally-occurringelements on the Periodic Table.
>>> You look at what’s not on the Lists – all I can say is that Hydrogen and Oxygen must feel a little left out. <<<
Welcome to the Tech Metals Age – where we need a lot of different elements, and a lot of each of them.
I said the challenge was huge – that’s one part of it. The sheer number of metals and minerals.
With that in mind, think of the average U.S. Senator or Congressperson navigating this issue: You’re asking them – along with all their other issues – to know how to incentivize, essentially, domestic production of bulk of the Periodic Table. //
The second part – is what I call the co-product challenge. Our language has to change here – we used to talk about certain deposits having by-products – we used to talk about “minor metals.”
Those terms just don’t fit anymore.
Example: You have a Rare Earths project in Texas – Round Top, with considerable Australian investment I should add – and it has the full range of rare earths – but also lithium for EV batteries, uranium, beryllium, and gallium – for supercomputing chips.
What’s minor? What’s a by-product? Different application, different answers. And technology – materials science — will drive demand over time.
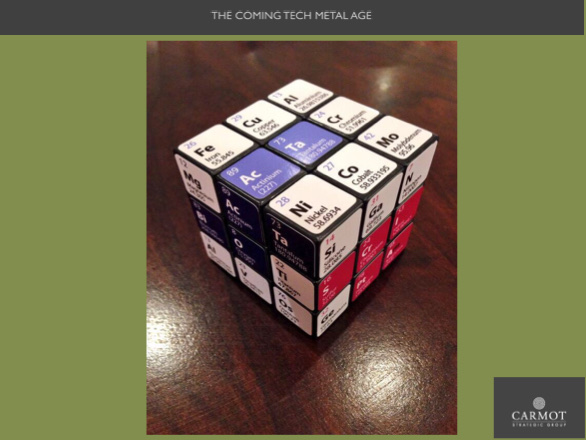
So: we’ve got to think of co-products – and how we can extract all of the useful metals and minerals from each deposit.
Take copper, for instance, which isn’t even on the U.S. or Australian lists. It’s the gateway to tellurium, rhenium and sometimes cobalt and perhaps even the rare earths. If you need those, then copper too is critical.
Then – the third challenge:
As we’ve heard today, each metal and mineral requires its own supply chain. Scores of them – not only to bring them out of the ground, but to process them into the advanced materials needed for all manner of tech apps.
So in the Rare Earths, certainly, but elsewhere as well — we’re seeing private sector players reaching out to partners — building out their own supply chains. It’s much more challenging than simply developing a mine.
And finally – the fourth challenge: While all that digging is going on – what’s going on above ground?
Geopolitics.
The tech metal age is going to redefine geopolitics. We’ll see the emergence of a new group of countries, tech metal “haves” and “have-nots.” The good news is that Australia and the U.S. are among the “haves” – because being among the “have-nots” is not a happy place to be.
My flight from Washington connected through Qatar. An amazing place – literally, castles in the sand. Built by energy resources. And all since 1940 – the date oil was first discovered there. I did a little Googling to see what the main economic driver was in Qatar before oil.
Pearl diving.
From pearls to oil – and in one generation Qatar was transformed.
Geopolitically, the tech metals will be transformative, too.
Are we ready for the emergence of new regions, new countries that will be defined by their tech metals status?
Should someone buy Greenland – should Greenland be For Sale? Or will Greenland become the tech metal Qatar of our 21st Century?
Do our public policies incentivize the private sector to spend the billions in Exploration and Development to find them, mine them, and bring them to market?
Which brings us to public policy. The final challenge I want to treat.
Remember that critical mineral “list of lists?”
It’s one thing to identify the metals and minerals we need. But what if – for some of them — those markets are so small as to be commercially uninteresting?
You can’t order the private sector to pursue and produce them.
At least the U.S. and Australia – and our democratic allies — can’t.
Governments have to incentivize – collaborate to seek creative ways to bring online new production where private companies may see only risk and little reward.
And it’s happening. Rio Tinto is working under a grant from the U.S. defense department to optimize rhenium recovery at its Kennecott copper smelter – and it’s collaborated with the U.S. Department of Energy on new ways to recover critical minerals from waste streams and historic tailings.
But the effort on the part of the U.S. Government has been episodic – not systematic, certainly not strategic.
I think now, though, that’s changing – we are entering a period of action. After a decade of inaction – we’re seeing a policy shift.
I can’t overstate the impact on the U.S. scene of the Presidential Defense Production Act Title III determinationin regard to encouraging rare earth production – not just mining but all along the supply chain, from mining to magnets.
It was wrongly reported by some of the early news storiesas a Presidential Executive Order – an exercise of American government authority that can be enacted by one president and undone by the next, lacking the permanence of a duly passed law. But Title III is law – it dates back to the Korean War, and confers on the president the authority to determine strategic need for a given material.
What are the tools of Title III? It gives the Secretary of Defense power to make direct investments – to support development of the material in question with loan guarantees – purchases for the Defense Stockpile, and even “commitments to purchase” – what we’d call offtakes.
In other words, Title III brings a warfighter focus – and a warfighter urgency. A broad “get it done” authority, after so many years of simply studying critical materials issues.
And I would hope that the dozen more metals and minerals for which the U.S. is 100% import dependent would be the focus of expanded Title III action.
And then there are the collaborative efforts between the U.S., Australia and Canada – under the umbrella of the NTIB, the National Technology Industrial Base – collaboration that is happening in real-time. Our three nations are remarkably resource-rich – and amount to nearly 30% of total global GDP. Our governments may be starting late, but no one should underestimate our abilities, once mobilized.
To the extent this scramble for tech metals takes on the form of a Tech War – metaphorically, one hopes — we need to recognize, borrowing from the language of military doctrine, that the Tech War is an Asymmetric War.
Rising powers like China are command economies. Even Russia, to the extent it plays a part in the Tech War, is what its leader likes to call a “managed democracy.” Delightful phrase.
The State backs enterprises, directly, or indirectly. Strategic goals around specific minerals can warrant a long-game in which the State covers losses on the way to driving out competitors and gaining market dominance.
In the nations based on free-markets, there’s no loss-making long game. There’s no “US 2025.” There’s only bankruptcy. No government props you up – far from it, just look at the tiny amounts of government aid on offer, certainly in the U.S.
So you might say — sounds like we’re destined to lose.
Not at all. State-controlled economies have their own downsides. They pick one path, and close the door on all the others.
Choosing control, they sacrifice creativity.
Over in the free market, we’re undisciplined, undirected, unpredictable – and because of that, we’re unconstrained and energetic and innovative.
…Just the attributes we need to prevail in an asymmetrical conflict. //
Which brings me to my final thought today.
…And Gordon: it goes straight to your comment about the “the ideological purity of the market”…
It’s a little reassurance from the author of an old book called The Wealth of Nations.
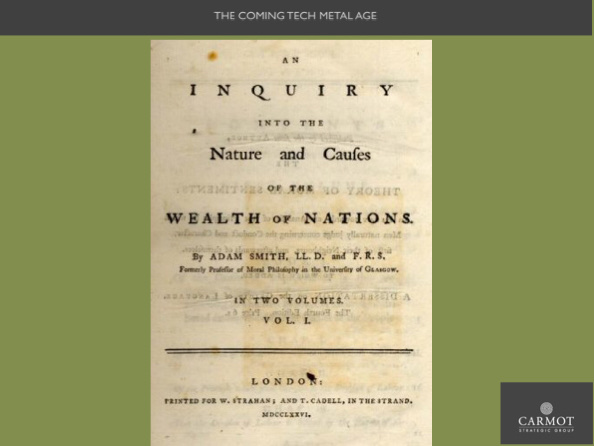
Even the father of the free market, Adam Smith – foresaw back in 1776 the challenge we face in our Tech Metals Age.
As much as he believed in free trade – he had what we would call a national security exception:
In the midst of his powerful defense of free markets, he said, when it comes to gunpowder and sailcloth – that is, the means of protecting British interests around the globe and projecting British power when needed….
…It’s best not to depend on others for your source of supply.
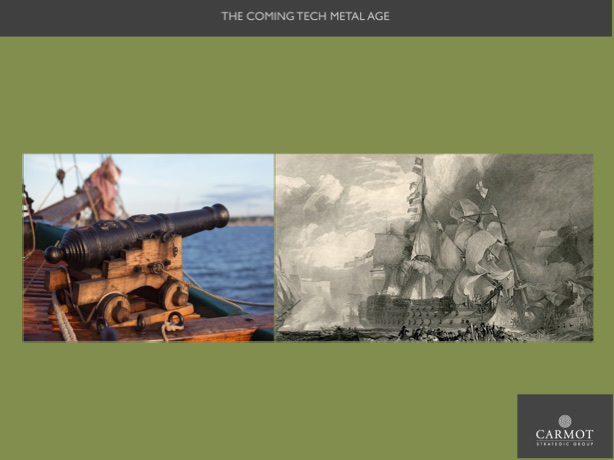
The need for gunpowder and sailcloth haven’t gone away:
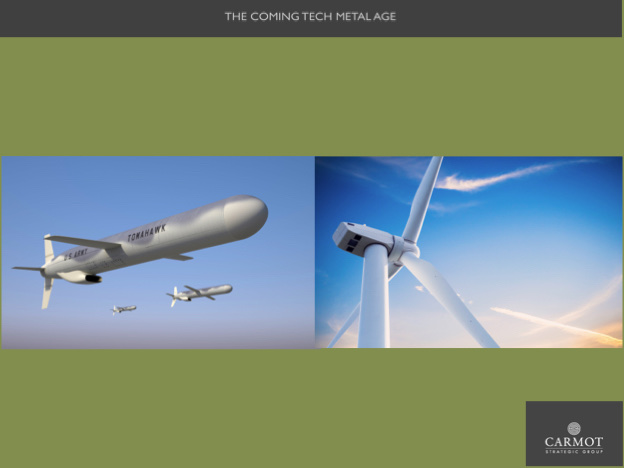
Our gunpowder is the hypersonic missile—and our sailcloth is a wind turbine
…they’re just updated for the 21st Century.
If we get this right – and we must, for the sake of our economies and our security, we must get this right – creative collaboration between the U.S. and Australia will be a big part of it.
And I’m pleased to be a small part of that here today.
###